मान लीजिए आपकी Loan EMI ₹20,000 है।
किसी वजह से lender आपको 3 महीने का Moratorium देता है और इस दौरान regular EMI देने की जरूरत नहीं पड़ती।
पहली नजर में यह राहत जैसा लगता है:
“3 महीने EMI नहीं देनी है, यानी 3 महीने का खर्च बच गया?”
लेकिन जरूरी नहीं।
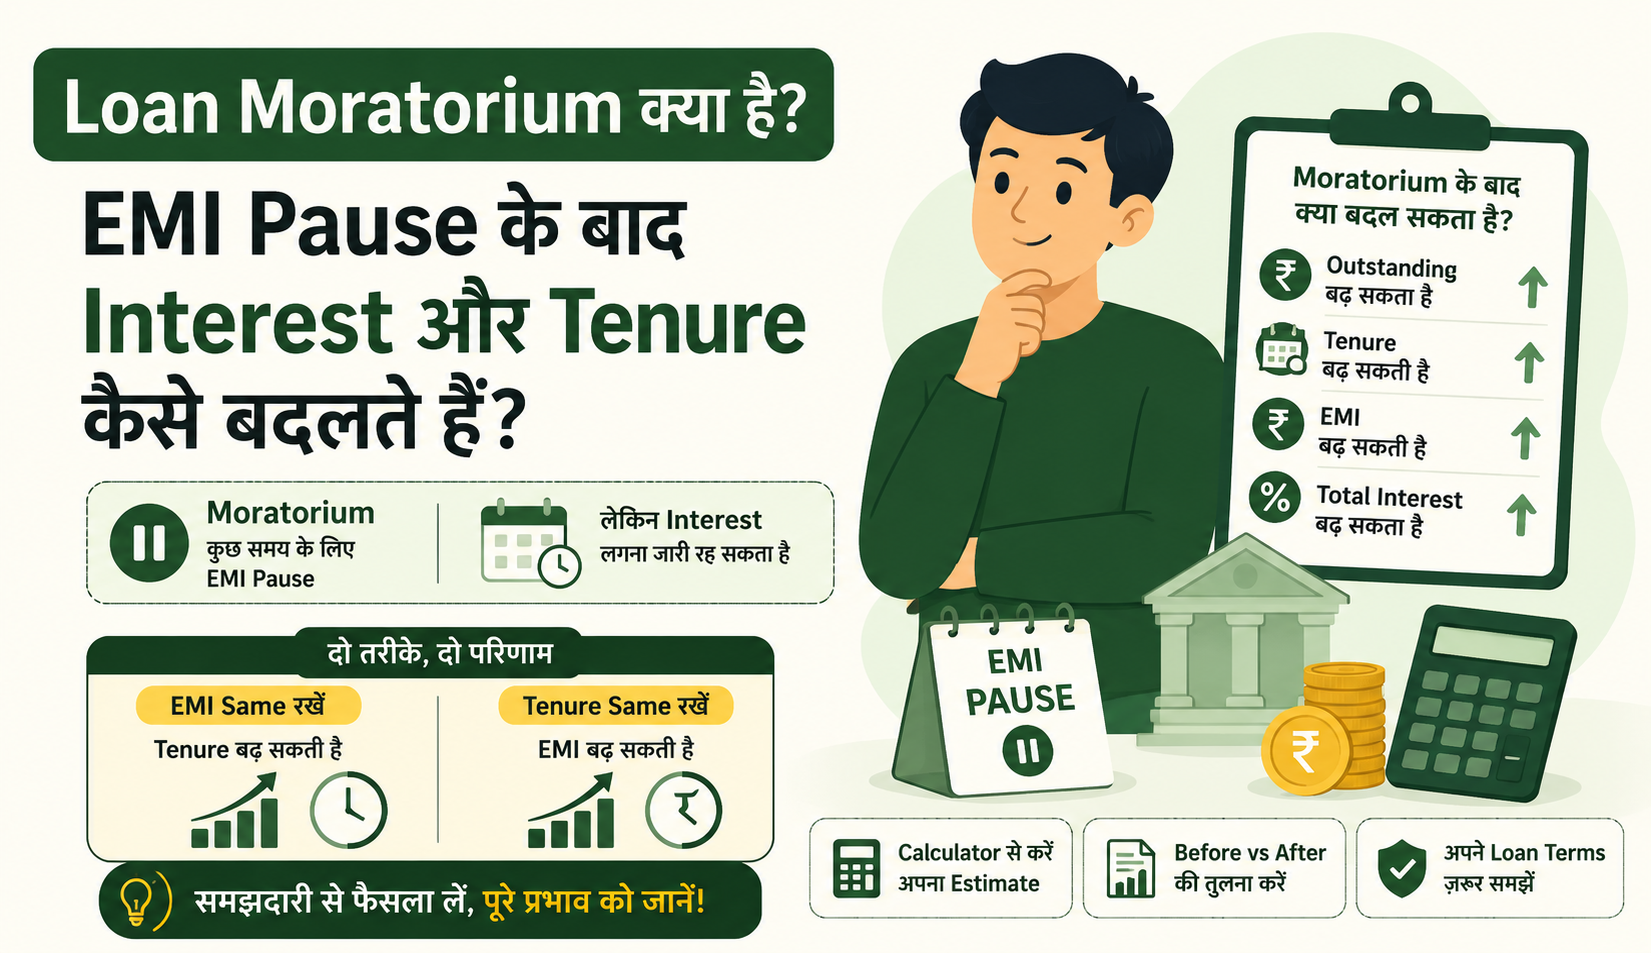
कई loan arrangements में Moratorium के दौरान EMI payment pause हो सकती है, लेकिन interest accrue होना जारी रह सकता है।
और यही interest बाद में आपके:
Outstanding Loan → EMI → Tenure → Total Interest
को प्रभावित कर सकता है।
इसलिए Moratorium को सिर्फ “EMI की छुट्टी” समझने के बजाय यह समझना जरूरी है कि pause के दौरान interest के साथ क्या हो रहा है।
Moratorium क्या होता है?
Loan Moratorium एक ऐसी अवधि हो सकती है जिसमें borrower को कुछ समय के लिए scheduled EMI/payment से राहत दी जाती है।
उदाहरण:
Regular EMI: ₹20,000
Moratorium: 3 months
इसका मतलब applicable loan terms के अनुसार 3 महीनों के लिए regular EMI payment defer हो सकती है।
लेकिन:
EMI Pause ≠ Interest Waiver
यह सबसे important distinction है।
Moratorium के दौरान interest कैसे calculate होगा, कब payable होगा और outstanding में add होगा या नहीं—यह lender, loan agreement और applicable terms पर depend करता है।
EMI नहीं दी तो Interest का क्या होता है?
इसे एक simple example से समझते हैं।
मान लीजिए Moratorium शुरू होने के समय:
Outstanding Loan: ₹10,00,000
Interest Rate: 10% p.a.
Approximate monthly rate:
10% ÷ 12 = 0.8333%
पहले महीने का approximate interest:
₹10,00,000 × 0.8333% ≈ ₹8,333
अब आगे क्या होगा, यह इस बात पर depend करता है कि Moratorium interest को कैसे treat किया जा रहा है।
हम educational comparison के लिए दो scenarios समझ सकते हैं।
Scenario 1: Interest Outstanding में Add होता है
इसे broadly interest capitalization के रूप में समझ सकते हैं।
अगर पहले महीने का ₹8,333 interest pay नहीं किया गया और outstanding में add हो गया, तो illustrative balance हो सकता है:
₹10,00,000 + ₹8,333 = ₹10,08,333
अब अगले महीने interest सिर्फ original ₹10 लाख पर नहीं, revised outstanding पर calculate हो सकता है।
Approximate second-month interest:
₹10,08,333 × 0.8333% ≈ ₹8,403
और balance फिर बढ़ सकता है।
इसलिए 3 महीने बाद outstanding सिर्फ:
₹10 लाख + ₹25,000
जैसा simple calculation जरूरी नहीं है।
अगर accrued interest periodically capitalize होता है, तो calculation sequential हो सकती है।
इसका मतलब?
Moratorium खत्म होने के बाद:
Outstanding पहले से ज्यादा हो सकता है।
और उस increased outstanding को repay करने के लिए EMI या tenure में adjustment की जरूरत पड़ सकती है।
Scenario 2: Moratorium के दौरान Interest Pay करते रहें
दूसरी possible structure में principal repayment pause हो सकती है, लेकिन borrower accrued interest pay करता रहता है।
उदाहरण:
Outstanding: ₹10 लाख
Approx. monthly interest: ₹8,333
अगर applicable terms के अनुसार आप Moratorium period में यह interest pay करते हैं, तो principal outstanding broadly unchanged रह सकता है।
इस situation का post-Moratorium impact capitalization वाले scenario से अलग होगा।
इसलिए सिर्फ यह जानना कि:
“मुझे 3 महीने का Moratorium मिला है”
काफी नहीं है।
यह भी समझना जरूरी है:
“इन 3 महीनों के interest का treatment क्या होगा?”
Moratorium के बाद क्या होता है?
मान लेते हैं Moratorium के दौरान interest accrue होकर outstanding में add हो गया।
अब Loan को revised outstanding के साथ repay करना है।
यहाँ broadly दो scenarios समझे जा सकते हैं:
Option 1
EMI Same रखें → Tenure बढ़ सकती है
Option 2
Original Tenure रखें → EMI बढ़ सकती है
यही Moratorium का वास्तविक long-term impact समझने का महत्वपूर्ण हिस्सा है।
Option 1: EMI Same → Loan Tenure बढ़ सकती है
मान लीजिए Moratorium से पहले आपकी EMI:
₹20,000
थी।
Moratorium के बाद outstanding बढ़ गया, लेकिन EMI लगभग ₹20,000 ही रखी जाती है।
अब वही EMI higher outstanding को repay करेगी।
इसलिए Loan को खत्म होने में ज्यादा समय लग सकता है।
Conceptually:
EMI Same
↓
Outstanding Higher
↓
More Repayment Months
↓
Potentially Higher Total Interest
यानी 3 महीने की payment pause का असर सिर्फ 3 महीने तक सीमित होना जरूरी नहीं है।
Loan की overall duration भी बढ़ सकती है।
Option 2: Tenure Same → EMI बढ़ सकती है
अब मान लीजिए आप original Loan completion timeline को broadly maintain करना चाहते हैं।
लेकिन Moratorium के बाद outstanding पहले से ज्यादा है।
Remaining months कम हो चुके हैं और repay करने के लिए balance ज्यादा हो सकता है।
ऐसी स्थिति में revised EMI बढ़ सकती है।
Conceptually:
Original Tenure Same
↓
Higher Outstanding
↓
Higher Revised EMI
इसमें Loan की duration ज्यादा नहीं बढ़ती, लेकिन monthly cash-flow burden बढ़ सकता है।
EMI Same या Tenure Same — कौन बेहतर?
इसका universal answer नहीं है।
दोनों का impact अलग है।
Moratorium के बाद | संभावित असर |
|---|---|
EMI Same | Remaining tenure बढ़ सकती है |
Tenure Same | Revised EMI बढ़ सकती है |
Interest Capitalized | Outstanding बढ़ सकता है |
Interest Paid During Moratorium | Outstanding impact comparatively अलग हो सकता है |
अगर monthly cash flow अभी भी tight है, तो EMI increase uncomfortable हो सकती है।
दूसरी तरफ, EMI same रखने से Loan ज्यादा समय तक चल सकता है और overall interest cost बढ़ सकती है।
इसलिए FinMitraPro का उद्देश्य किसी एक option को “best” बताना नहीं है।
पहले दोनों scenarios के numbers समझें।
एक Simple Example
मान लीजिए:
Loan Amount: ₹10,00,000
Interest Rate: 10% p.a.
Original Tenure: 10 Years
Moratorium: 3 Months
अब मान लेते हैं Moratorium Loan की शुरुआत में लिया गया और इस दौरान interest outstanding में add होता है।
Approximate first-month interest:
₹8,333
फिर interest revised balance पर calculate हो सकता है।
3 महीने बाद outstanding original ₹10 लाख से ऊपर जा सकता है।
अब दो possibilities देखें:
EMI Same रखें
Original EMI broadly same रहती है।
लेकिन revised outstanding repay करने के लिए additional months लग सकते हैं।
Tenure Same रखें
Original completion timeline maintain करने की कोशिश की जाती है।
लेकिन remaining repayment period में higher outstanding repay करने के लिए EMI बढ़ सकती है।
Exact numbers आपके loan assumptions पर depend करेंगे—इसीलिए interactive calculator useful है।
Moratorium का Impact खुद Calculate करें
FinMitraPro Loan EMI Calculator में Add Moratorium option खोलें।
आप enter कर सकते हैं:
Loan Amount
Interest Rate
Loan Tenure
फिर Moratorium section में:
Moratorium कितनी EMIs के बाद शुरू होगा?
Moratorium कितने महीनों का है?
Moratorium Interest Treatment
Interest Capitalize
Pay Interest
और उसके बाद:
Keep EMI Same → Extend Tenure
या
Keep Original Tenure → Recalculate EMI
Calculator estimated impact दिखा सकता है:
Outstanding before Moratorium
Outstanding after Moratorium
Interest accrued during Moratorium
Original EMI
Revised EMI
Original tenure
Revised tenure
Extra repayment months
Estimated additional interest
इससे सिर्फ “3 महीने EMI नहीं देनी” के बजाय पूरी repayment picture समझ आती है।
Moratorium Loan के बीच में मिले तो?
Moratorium जरूरी नहीं कि Loan की शुरुआत में ही हो।
मान लीजिए:
Original Loan: ₹20 लाख
Moratorium starts after: 24 EMIs
तब calculation original ₹20 लाख से दोबारा शुरू नहीं होनी चाहिए।
पहले calculate होगा:
Original Loan
↓
24 Regular EMIs
↓
Outstanding after EMI #24
↓
Moratorium Period
↓
Interest Treatment
↓
Revised Outstanding
↓
Revised Repayment Schedule
यानी Moratorium का impact उस समय के actual outstanding पर calculate होना चाहिए।
Repayment Schedule क्यों जरूरी है?
सिर्फ final EMI या tenure देखकर पूरी कहानी नहीं समझ आती।
मान लीजिए Moratorium EMI #12 के बाद शुरू होता है।
Schedule broadly ऐसा दिखाई दे सकता है:
EMI #11 → Normal EMI
EMI #12 → Normal EMI
Month #13 → Moratorium
Month #14 → Moratorium
Month #15 → Moratorium
Month #16 → Regular repayment resumes
अगर interest capitalize हो रहा है, तो Moratorium के हर महीने outstanding बदल सकता है।
इसलिए revised repayment schedule यह समझने में मदद करता है कि:
Interest कितना बढ़ा?
Outstanding कितना बदला?
Repayment कब resume हुई?
Loan कब खत्म होगा?
3 महीने का Moratorium = सिर्फ 3 Extra EMIs?
जरूरी नहीं।
यह एक common misunderstanding हो सकती है।
अगर Moratorium 3 महीने का है, तो इसका मतलब automatically यह नहीं कि Loan सिर्फ 3 महीने extend होगा।
क्योंकि Moratorium period में accrued/capitalized interest outstanding बढ़ा सकता है।
अगर EMI same रहती है, तो higher outstanding को repay करने में 3 महीने से ज्यादा additional time भी लग सकता है।
Exact impact calculation पर depend करेगा।
क्या Moratorium Free होता है?
“Free” शब्द से बचना बेहतर है।
Moratorium का मतलब payment deferment हो सकता है।
अगर interest continue होता है, तो repayment की timing बदलने के साथ overall borrowing cost भी बदल सकती है।
इसलिए Moratorium offer देखते समय पूछें:
क्या सिर्फ EMI postpone हो रही है या interest भी waive हो रहा है?
दोनों बहुत अलग बातें हैं।
Moratorium और EMI Holiday एक ही चीज हैं?
Marketing communication में अलग-अलग terms दिखाई दे सकती हैं, जैसे:
Moratorium
Payment Holiday
EMI Holiday
Repayment Pause
लेकिन सिर्फ नाम देखकर financial treatment assume नहीं करना चाहिए।
Check करें:
Principal payment pause है?
Interest continue होगा?
Interest कब payable होगा?
Interest outstanding में capitalize होगा?
EMI बदलेगी?
Tenure बढ़ेगी?
कोई additional charge है?
Actual loan agreement/lender communication सबसे important है।
Moratorium Credit Score को प्रभावित करेगा?
इसका simple universal answer देना सही नहीं होगा।
Impact इस बात पर depend कर सकता है कि payment relief lender द्वारा formally approved है या borrower बिना approval EMI miss कर रहा है।
Approved Moratorium
और
Unpaid / Missed EMI
एक ही चीज नहीं हैं।
इसलिए payment रोकने से पहले lender से written confirmation लेना महत्वपूर्ण है।
अगर कोई borrower सिर्फ यह मानकर EMI रोक देता है कि Moratorium available होगा, तो consequences अलग हो सकते हैं।
Moratorium कब useful हो सकता है?
Moratorium का उद्देश्य temporary cash-flow pressure में repayment relief देना हो सकता है।
उदाहरण:
temporary income disruption
business cash-flow issue
unexpected financial stress
lender-approved restructuring
specific product terms
लेकिन इसका मतलब यह नहीं कि हर borrower को available Moratorium लेना चाहिए।
Decision लेते समय दो अलग questions देखें:
आज का सवाल
क्या मुझे अभी EMI payment relief की जरूरत है?
Future का सवाल
इस relief की वजह से मेरी future EMI, tenure और total interest पर क्या असर पड़ेगा?
दोनों equally important हैं।
Moratorium vs Emergency Fund
यह comparison भी useful है।
अगर temporary cash-flow problem है और आपके पास emergency fund available है, तो decision सिर्फ calculator का नहीं है।
आपको liquidity और future loan cost दोनों देखनी होंगी।
दूसरी तरफ, पूरा emergency fund खत्म करके EMI pay करना भी हर situation में appropriate नहीं होगा।
इसलिए objective यह नहीं होना चाहिए:
“Moratorium हमेशा avoid करें।”
या:
“Cash बचाने के लिए Moratorium ले लें।”
Better approach है:
Immediate cash-flow relief और future borrowing cost दोनों समझें।
Moratorium लेते समय किन चीजों को जरूर check करें?
Loan statement या lender communication में इन questions के answers देखें:
1. Moratorium कितने महीनों का है?
2. कब से शुरू होगा?
3. इस दौरान interest accrue होगा?
4. Accrued interest outstanding में add होगा?
5. Interest अलग से pay करने का option है?
6. Moratorium के बाद EMI बढ़ेगी या tenure?
7. कोई additional fee/charge है?
8. Revised repayment schedule मिलेगा?
9. Credit bureau reporting कैसे handle होगी?
10. Early repayment/Part-Payment के options क्या हैं?
इन details के बिना सिर्फ “3 months EMI holiday” देखकर decision लेना अधूरा हो सकता है।
Moratorium खत्म होने के बाद क्या check करें?
Repayment resume होने से पहले revised Loan details verify करें।
विशेष रूप से:
Outstanding Principal
Revised EMI
Remaining Tenure
Next EMI Date
Interest Capitalized
Additional Interest
Revised Repayment Schedule
अगर lender का revised schedule और आपका estimate अलग है, तो lender से calculation समझना बेहतर है।
FinMitraPro calculator educational estimate देता है; lender statement contractual figure होता है।
सबसे Important बात
Moratorium का सबसे बड़ा benefit immediate cash-flow relief हो सकता है।
लेकिन उस relief की future cost हो सकती है।
इसलिए सिर्फ यह मत देखें:
“अगले 3 महीने ₹20,000 EMI नहीं जाएगी।”
यह भी देखें:
“इन 3 महीनों के बाद मेरा outstanding, EMI, tenure और total interest कितना बदल सकता है?”
यही Moratorium को समझने का ज्यादा complete तरीका है।
📖 Summary
1. Moratorium में EMI/payment temporarily pause हो सकती है, लेकिन interest automatically waive नहीं होता।
2. अगर Moratorium interest outstanding में capitalize होता है, तो Loan balance बढ़ सकता है।
3. Moratorium के बाद EMI same रखने पर Loan tenure बढ़ सकती है।
4. Original tenure maintain करने पर revised EMI बढ़ सकती है।
5. Moratorium की actual cost उसके duration, interest treatment, outstanding balance और post-Moratorium repayment structure पर depend करती है।
6. Approved Moratorium और बिना approval EMI miss करना एक ही चीज नहीं है।
7. Moratorium लेने से पहले lender की terms और revised repayment impact समझना जरूरी है।
FinMitraPro Note
Moratorium को सिर्फ:
“EMI से 3 महीने की छुट्टी”
की तरह मत समझिए।
इसे ऐसे समझना ज्यादा useful है:
आज EMI का pressure कम हो सकता है, लेकिन कल outstanding, EMI, tenure या total interest बदल सकता है।
इसलिए Moratorium लेने से पहले Before vs After numbers जरूर समझें।